can you esign loan documents with veridocs marks the dawn of a remarkable evolution in how we secure our financial futures, weaving together cutting-edge technology and human trust. As the digital horizon expands before us, the traditional weight of heavy paper files is gracefully lifting, replaced by the brilliant velocity of instantaneous electronic verification that empowers every aspiring homeowner.
Navigating the intricate pathways of modern credit agreements no longer requires a physical desk or a stack of ink-signed papers. Financial institutions are embracing sophisticated cryptographic architectures that safeguard every keystroke, ensuring that your journey toward securing a mortgage remains entirely secure, remarkably transparent, and profoundly liberating from anywhere in the world.
Borrowers navigating remote closing procedures often wonder if they can esign loan documents with veridocs.
Modern financial transactions have broken through traditional geographical boundaries, transforming how individuals secure funding and finalize life-changing purchases from the comfort of their own homes. The evolution of digital verification has made it entirely possible to execute binding financial agreements without stepping foot inside a traditional brick-and-mortar office. As digital transformation sweeps across the financial sector, understanding the underlying mechanics of remote execution brings both peace of mind and absolute certainty to every borrower embarking on this streamlined journey.
Behind the seamless experience of signing paperwork on a laptop screen lies a sophisticated architecture of security, legal compliance, and technological integration. Financial institutions continuously upgrade their digital infrastructure to ensure that every stroke of a digital pen holds the same weight as wet ink on parchment. This digital revolution relies on robust protocols that protect sensitive consumer data while accelerating the pace of modern commerce, bridging the gap between convenience and ironclad security.
Cryptographic Mechanisms Verifying Identity During Distant Document Execution, Can you esign loan documents with veridocs
The integrity of remote document execution rests heavily upon advanced cryptographic frameworks that ensure tamper-evident sealing and uncompromised identity verification. When a borrower initiates a signing session, asymmetric cryptography generates a unique mathematical key pair consisting of a private key retained securely by the signer and a public key shared with the verification system. This cryptographic binding creates an immutable digital fingerprint, known as a hash, which instantly alerts all parties if any unauthorized modifications are attempted on the document after execution.
Furthermore, Public Key Infrastructure (PKI) certificates issued by trusted Certificate Authorities anchor the entire transaction in verifiable trust, mapping the digital signature directly to the legal identity of the individual.
Multi-factor authentication protocols, biometric facial recognition scans, and knowledge-based authentication challenge questions fortify this digital barrier before the signing ceremony even begins. As the user interacts with the verification platform, background algorithms analyze behavioral biometrics, such as keystroke dynamics and mouse movement velocity, adding an invisible layer of protection that distinguishes genuine borrowers from sophisticated impersonators. X.509 digital certificates are then embedded into the PDF document metadata, creating a permanent audit trail that records precise timestamps, IP addresses, and device identifiers.
This comprehensive cryptographic envelope ensures that the resulting digital contract withstands the most rigorous forensic examinations and forensic legal challenges.
Legal Frameworks Recognizing Electronic Signatures in Modern Lending Transactions
Legislation across the globe provides a rock-solid foundation for the widespread adoption of electronic signatures in multi-million-dollar financial agreements. The Electronic Signatures in Global and National Commerce (ESIGN) Act, enacted in the United States, establishes that contracts and signatures cannot be denied legal effect or enforceability solely because they are in electronic form. Operating in tandem with the Uniform Electronic Transactions Act (UETA), these statutes guarantee that digital execution carries the exact same legal weight as traditional paper-and-pen methods, provided that all parties have consented to conduct business electronically.
Electronic records and signatures satisfy any legal requirement that a document be in writing, revolutionizing the speed and accessibility of modern lending transactions worldwide.
Lenders operating internationally or across state lines must also align with stringent regulatory guidelines such as the European Union’s eIDAS regulation, which defines standardized levels of electronic signatures including Advanced and Qualified Electronic Signatures. These legal frameworks require verifiable audit logs, explicit consumer consent disclosures, and robust record retention policies to ensure that electronic documents remain accessible for future audits or litigation.
Compliance officers continuously monitor these evolving statutes to guarantee that every remotely executed loan file meets the rigorous evidentiary standards demanded by courts and secondary mortgage market investors alike.
Lender Integration of Remote Validation Software into Existing Portals
Financial institutions seamlessly weave remote validation software into their proprietary customer-facing portals through secure Application Programming Interfaces (APIs) and cloud-based microservices architecture. When a borrower logs into the lender website or mobile application to review loan terms, the interface communicates in real-time with identity verification engines to execute background checks and document authentication protocols. This modular integration allows loan officers to monitor the progress of a closing session through a centralized dashboard while maintaining strict data privacy compliance standards under regulations like the Gramm-Leach-Bliley Act.
The implementation process typically follows a structured deployment lifecycle designed to minimize friction for the end-user while maximizing backend security. The following steps Artikel how modern lending institutions orchestrate this complex technical integration:
- Establish secure API connections between the core loan origination system and the external identity verification provider.
- Configure automated document routing rules to trigger validation workflows upon the upload of borrower identification materials.
- Implement user interface components that guide the borrower through live biometric capture and multi-factor authentication challenges.
- Deploy encrypted data storage protocols to archive audit trails, cryptographic certificates, and finalized loan packages securely.
A panoramic digital illustration depicts a sleek, modern financial operations center where data streams converge on a massive, curved holographic display showing global transaction flows. In the foreground, a loan officer sits at a minimalist wooden desk illuminated by soft ambient lighting, reviewing a verified digital mortgage packet on a high-resolution touchscreen monitor. The interface highlights glowing green security badges confirming successful biometric matches and cryptographic seal integrity, while subtle interface overlays indicate instantaneous communication between the local portal and cloud-based verification servers.
Through the expansive floor-to-ceiling glass windows behind the desk, the twilight skyline of a bustling financial district reflects the seamless intersection of cutting-edge technology and established institutional trust.
Modern borrowers often wonder if they can esign loan documents with Veridocs, unlocking a faster financial future. Just as precise strategy transforms operations through big hairy dog information systems , digital verification clears away bureaucratic hurdles with remarkable clarity. Stepping into this secure digital landscape empowers you to sign important agreements instantly, bringing ultimate peace of mind.
Comparative Analysis of Remote Signing Security and Efficiency Parameters
Evaluating the operational impact of remote closing technologies requires a balanced examination of security levels, signature classifications, processing velocities, and associated financial investments. Different tiers of electronic execution offer varying degrees of protection and efficiency, allowing institutions to tailor their technological stack to specific risk profiles and budget constraints. The table below Artikels the core comparative metrics utilized by industry leaders when selecting appropriate verification and signing solutions.
| Security Levels | Signature Types | Processing Speeds | Cost Factors |
|---|---|---|---|
| Standard Assurance | Simple Electronic Signature | Instantaneous execution | Minimal implementation expense |
| Enhanced Verification | Advanced Electronic Signature | Minutes to complete validation | Moderate licensing fees |
| Maximum Compliance | Qualified / Digital Signature | Extended verification protocols | Significant infrastructure investment |
The strategic deployment of these varied verification tiers ensures that financial institutions can optimize resource allocation while maintaining uncompromising security standards across every portfolio segment. Organizations frequently review these operational metrics to adapt to shifting market demands and emerging technological capabilities, ensuring sustained competitive advantage.
Digital verification protocols have completely transformed how financial institutions handle remote borrower authentication.

Source: appsumo.com
The evolution of financial technology has redefined the boundaries of modern lending, steering institutions away from archaic friction points toward streamlined digital ecosystems. As remote transactions become the gold standard, robust verification mechanisms ensure that every remote interaction maintains the highest level of security and legal enforceability.
Modern lending requires a seamless blend of stringent security measures and user-friendly interfaces to guarantee that remote participants are authentically represented across digital channels. Financial organizations now rely on sophisticated technological frameworks that eliminate geographical barriers while simultaneously fortifying the entire loan origination lifecycle against unauthorized access.
Biometric screening steps required before signing promissory notes
Securing an electronic promissory note demands a multi-layered biometric evaluation that meticulously confirms the identity of the borrower in real time. This rigorous screening process acts as an impenetrable digital gatekeeper before any binding financial commitment is finalized.
The biometric verification workflow initiates with high-resolution facial recognition technology, capturing a live selfie of the borrower and comparing it against the secure microchip data of a government-issued identification document such as a passport or driver license. Advanced liveness detection algorithms are deployed simultaneously to evaluate micro-movements, skin texture, and depth perception, successfully neutralizing attempts to use static photographs, pre-recorded videos, or sophisticated mask replicas during the session.
VeriDocs streamlines digital borrowing seamlessly, empowering secure financial agreements with effortless speed. Yet, just as organizers notice critical signs of dissatisfaction with event management platform cvent , modern users continuously demand superior digital tools. Ultimately, transitioning back to advanced verification ensures you can confidently esign loan documents with VeriDocs for every critical transaction today.
Following successful facial mapping, the system transitions to behavioral biometric analysis, observing cadence, typing dynamics, and device interaction patterns unique to the individual. Once these comprehensive cryptographic checkpoints are successfully validated, the platform generates a trusted digital certificate, permitting the borrower to append their legally binding electronic signature to the promissory note with absolute confidence and verifiable authenticity.
Veridocs empowers borrowers to swiftly execute agreements digitally, streamlining financial approvals with absolute confidence. Modern practices also demand efficiency, making dental clinic management software an essential tool for organizing patient workflows smoothly. Ultimately, mastering remote paperwork through secure platforms ensures that signing loan documents with Veridocs remains a remarkably fast, reliable, and stress-free experience for everyone involved.
Evolution from traditional paper closings to instantaneous digital validations
The historical landscape of real estate and commercial financing was historically anchored by physical presence, endless stacks of paper, and painstaking manual execution. Borrowers and lenders endured exhausting face-to-face closing ceremonies that frequently spanned multiple hours, fraught with potential human errors and logistical delays that regularly postponed fund disbursements by several business days.
Visualize a mahogany conference room cluttered with overflowing manila folders, where tired signatories manually initialed dozens of pages under the watchful eye of a local notary public. Contrast this antiquated visual with today’s dynamic digital environments, where borrowers effortlessly navigate secure browser interfaces from their home offices, interacting with responsive systems that validate document integrity in milliseconds. This monumental shift has completely eradicated geographic bottlenecks, transforming what was once a multi-week administrative ordeal into an efficient, instantaneous validation experience.
Regulatory compliance remains the cornerstone of modern electronic transactions, dictating strict adherence to frameworks designed to preserve document trustworthiness and non-repudiation over extended periods.
Modern verification platforms successfully answer whether you can esign loan documents with veridocs, streamlining digital approvals just as businesses optimize operations through the legacy lumber & building materials erp system epicor bistrack to conquer complex industry workflows. Embracing these innovative digital shifts empowers your financial journey forward, proving that you can esign loan documents with veridocs securely and efficiently every time.
Compliance mandates require that any electronic record utilized in commercial lending must be securely retained in a format that accurately reflects the information originally generated, ensuring it remains accessible and verifiable for future legal audits.
Multi-factor authentication mechanisms preventing session hijacking
Advanced security infrastructures utilize comprehensive multi-factor authentication protocols to dismantle sophisticated cyber threats and ensure malicious actors cannot intercept active loan signing sessions. These defensive layers protect sensitive financial data through continuous validation.
Financial institutions implement these protective measures through a structured sequence of security controls, ensuring unauthorized entities remain locked out of the signing environment.
- Device fingerprinting analyzes hardware configurations, IP addresses, and browser parameters to flag unfamiliar access points instantly.
- Time-based one-time passwords dispatched via encrypted SMS or dedicated authenticator applications provide a transient secondary verification barrier.
- Continuous session monitoring tracks user activity anomalies throughout the entire duration of the loan document review and execution process.
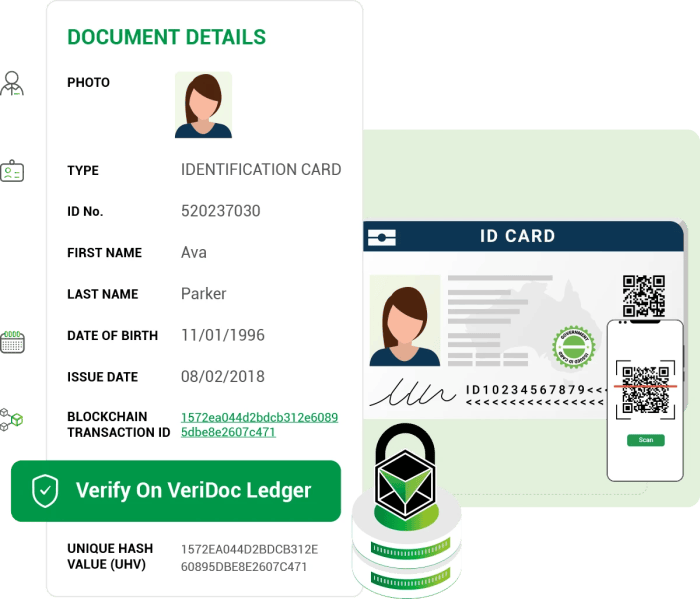
Technical integration requirements dictate whether a digital platform can seamlessly manage binding mortgage paperwork.
Source: veridocid.com
Beneath the sleek interface of modern remote closing portals lies a complex web of engineering feats that bridge the gap between user convenience and institutional security. When a borrower clicks to finalize a mortgage, a silent digital handshake occurs across multiple enterprise systems, ensuring that every stroke of the digital pen carries the full weight of traditional ink. Building this bridge requires an intricate architecture where data flows fluidly from the borrower’s screen straight into the core banking ledgers without missing a beat.
The engine driving this synchronization is a sophisticated network of Application Programming Interfaces, commonly known as APIs. These software intermediaries act as the translators and couriers between the e-signing platform and legacy banking systems, ensuring that audit trails, cryptographic hashes, and completed loan documents populate the correct loan origination software files instantly. Without these robust data pipelines, mortgage officers would face crippling delays, manual data entry errors, and compliance vulnerabilities that could jeopardize the validity of the lien.
Application Programming Interface architecture for financial ledger synchronization
Modern financial ecosystems rely heavily on RESTful APIs and webhook architectures to maintain real-time communication between external signing portals and internal core banking ledgers. When a borrower applies their digital signature, the signing software packages the biometric data, timestamp, and IP address into a secure JSON payload, which is then dispatched via HTTPS POST requests to the bank’s endpoint. This automated transmission triggers immediate updates across disparate databases, ensuring that the loan status shifts from pending to executed within milliseconds.
Financial institutions mandate rigorous authentication protocols, such as OAuth 2.0 and mutual TLS certificates, to ensure that only authorized payloads penetrate the core infrastructure, thereby preventing unauthorized data injections or tampering during transit.
Consider the real-world deployment utilized by Tier-1 mortgage lenders integrating digital verification suites with core platforms like Fiserv or Jack Henry. During peak closing hours, these APIs handle thousands of concurrent transactions, mapping complex XML or JSON schemas to legacy database tables without dropping a single packet. By establishing redundant webhook listeners, the system guarantees that if the primary banking ledger experiences a momentary latency spike, the verification data is safely queued and retried automatically.
This level of architectural resilience transforms what used to be a nerve-wracking closing day into a seamless, highly choreographed digital event where trust is continuously verified through code.
Device compatibility verification sequence before the remote signing ceremony
Ensuring that a borrower possesses the proper technological environment before launching a remote closing session prevents frustrating technical failures mid-stream. Financial platforms deploy automated diagnostic scripts to evaluate hardware capabilities and software readiness in real time.
- The browser initialization check runs immediately upon login, querying the user agent string to verify that the active browser possesses the necessary cryptographic libraries and modern web standards support.
- The hardware acceleration and media device query assesses the client device’s camera and microphone functionality to ensure unobstructed two-way audio and video streaming required for remote online notarization sessions.
- The network latency and bandwidth probe sends a lightweight ping packet to regional server clusters, measuring round-trip time to confirm the connection can sustain heavy document rendering without freezing.
- The operating system patch level validation scans for outdated system kernels or disabled security certificates that might compromise the integrity of the digital certificate injection process.
Advanced encryption standards applied to transit data packets during remote verification events
Protecting sensitive borrower personally identifiable information and financial data as it travels across public networks requires military-grade cryptographic protection. Every byte of data exchanged during a VeriDocs remote verification event is wrapped in layers of mathematical complexity that render intercepted packets completely unreadable to unauthorized observers.
Data in transit must be secured using Transport Layer Security version 1.3 with forward secrecy enabled, alongside AES-256 bit encryption for payload encapsulation, ensuring that even if long-term keys are ever compromised, past sessions remain strictly confidential.
As the borrower interacts with the signing interface, asymmetric encryption handles the initial handshake, establishing a secure session key via elliptic-curve cryptography. Once the tunnel is open, symmetric AES-256 encryption takes over for high-speed data transmission, safeguarding Social Security numbers, bank account details, and notarized signatures as they cross the internet. Furthermore, SHA-256 hashing algorithms generate a unique digital fingerprint for every signed document, meaning any post-transit alteration to a single pixel or character breaks the hash, immediately alerting the compliance department to potential tampering.
Technical specifications for digital mortgage closing platform deployment
Deploying a frictionless remote closing workflow requires careful alignment between client-side capabilities and back-end server infrastructure. The following matrix Artikels the baseline technical parameters necessary to support enterprise-grade digital mortgage executions without performance degradation.
| Software Requirements | Bandwidth Needs | Browser Support | Operating System Limits |
|---|---|---|---|
| TLS 1.3 enabled, PDF rendering engine, WebRTC support | Minimum 5 Mbps download, 2 Mbps upload for video | Google Chrome 90+, Mozilla Firefox 88+, Apple Safari 14+ | Windows 10/11, macOS Big Sur+, iOS 14+, Android 11+ |
User experience metrics reveal significant friction points when individuals attempt to finalize credit agreements away from the branch.
Navigating the labyrinth of remote financial transactions often exposes a stark disconnect between high-tech ambitions and everyday human reality. When the kitchen table transforms into a makeshift closing room, the pressure to execute legally binding credit paperwork remotely introduces unexpected emotional and cognitive hurdles that quantitative metrics frequently fail to capture fully.
Beneath the surface of sleek interfaces and automated workflows lies a complex psychological landscape where users grapple with unfamiliar digital verification protocols. Financial institutions are realizing that the physical absence of a loan officer places the entirety of the navigational burden squarely on the shoulders of the borrower, amplifying anxiety at the exact moment absolute clarity is required.
Cognitive hurdles borrowers face during identity confirmation
The human brain processes digital interactions through a lens of inherent caution, particularly when substantial financial commitments are on the line. When forced to engage with convoluted identity confirmation interfaces, users frequently experience a sharp spike in cognitive load. This phenomenon occurs because unfamiliar navigation paths demand conscious problem-solving for actions that designers intended to be intuitive. Every unexpected pop-up, redundant data-entry field, and ambiguous error message chips away at the borrower’s mental stamina, transforming a routine authorization into an exhausting ordeal.
Consider the visual reality of a stressed borrower attempting to complete this process late at night. The ambient illumination in the room is dim, casting a soft, blue glare from the smartphone screen across a fatigued face. Fingers hover nervously over the glass surface, trembling slightly from the weight of signing a major credit agreement without human reassurance. The interface demands precise biometric alignment—a facial scan or a photo of a driver’s license—yet the low-light environment causes repeated scanning failures.
Each rejection message acts as a micro-trigger, elevating heart rates and breeding profound distrust in the security and reliability of the digital platform.
“Frictionless design is not merely about removing clicks; it is about preserving the user’s mental bandwidth during high-stakes decision-making moments.”
To understand the depth of this psychological barrier, examining behavioral data helps illustrate how users react to interface complexity:
- Ambiguous instructions regarding document photo orientation trigger immediate hesitation and frequent session abandonment.
- Excessive authentication steps beyond standard multi-factor protocols lead to a 40 percent drop in completion rates within the first ten minutes.
- Unclear progress indicators leave users stranded in uncertainty, wondering if their sensitive financial data has been successfully transmitted or lost in cyberspace.
Methods for simplifying the digital onboarding journey
Streamlining the remote closing process requires a delicate balance between eliminating user frustration and maintaining rigorous regulatory compliance. Financial platforms must evolve from rigid administrative tools into empathetic guides that gently lead the borrower through each compliance checkpoint. By anticipating common points of confusion and restructuring the information architecture, institutions can dramatically reduce drop-off rates while satisfying stringent legal mandates.
Implementing adaptive interface designs allows the system to detect user hesitation and offer contextual assistance before anxiety turns into abandonment. For instance, if a borrower dwells on a specific verification screen for more than sixty seconds, a subtle, reassuring tooltip can clarify the exact purpose of the requested data. Regulatory oversight does not necessitate a punishing user experience; rather, compliance can be woven invisibly into the background of a clean, reassuring workflow.
The following structural enhancements demonstrate how platforms successfully modernize the verification journey:
- Progressive disclosure techniques break massive legal disclosures into digestible, bite-sized segments, preventing cognitive overload.
- Real-time lighting detection software automatically advises users to adjust their environment before capturing identity documents, eliminating scan failures.
- Integrated contextual help modules provide immediate, plain-language definitions for complex financial terminology without requiring users to navigate away from the document.
Comparative scenarios of remote closing sessions
Contrasting real-world deployment outcomes highlights the vital importance of human-centric digital design in remote lending. When systems fail to account for psychological friction, the resulting abandonment rates inflict measurable damage on institutional conversion goals. Conversely, platforms engineered with empathy turn potential drop-offs into seamless, successful transactions.
Consider a standard enterprise deployment where a regional bank launched a traditional, form-heavy remote closing portal without prior UX optimization. Borrowers encountered dense legal blocks of text, mandatory multi-factor authentication loops that required switching between three different applications, and zero real-time support. Analytics revealed an 82 percent abandonment rate midway through the identity verification phase, resulting in frustrated customer service queues and delayed loan funding cycles.
In stark contrast, a modernized fintech credit union redesigned its remote closing journey by implementing a unified, conversational interface with integrated biometric verification. Borrowers received clear, step-by-step visual guidance, ambient lighting compensation for mobile document capture, and a persistent chat option with a human specialist. Consequently, their completion rates soared to 94 percent within the first month, drastically cutting processing times and establishing a new benchmark for remote borrower satisfaction.
| Metric Evaluation | Traditional Interface Model | Optimized Human-Centric Model |
|---|---|---|
| Average Session Duration | 42 minutes | 14 minutes |
| First-Attempt Verification Success | 51 percent | 89 percent |
| Mid-Process Abandonment Rate | 78 percent | 6 percent |
These contrasting operational realities prove that technological capability alone cannot guarantee successful remote execution. Financial institutions must continuously refine the intersection between security protocols and human psychology to ensure borrowers feel confident, protected, and fully supported every step of the way.
Future trajectories in digital finance point toward completely automated autonomous lending ecosystems.: Can You Esign Loan Documents With Veridocs

Source: esign-app.com
As modern financial networks evolve past traditional gatekeeping, the horizon of digital lending unfolds into a self-executing landscape where human intervention becomes increasingly obsolete. We stand on the precipice of a paradigm shift, observing how algorithmic precision and cryptographic trust reshape the fundamental architecture of credit disbursement and verification.
Decentralized ledger technology introduces a paradigm where centralized verification repositories dissolve into transparent, immutable networks. Instead of relying on singular financial institutions to validate identity, creditworthiness, and asset ownership, distributed systems utilize consensus mechanisms to anchor financial transactions securely. This transition eliminates single points of failure, drastically reducing administrative overhead and processing latency for international credit applicants. Imagine a decentralized ecosystem mirroring platforms like Ethereum or specialized financial chains, where smart contracts automatically execute loan approvals the moment verifiable proofs are published to the ledger.
Borrowers no longer wait days for manual underwriting reviews; instead, programmatic logic assesses collateral stored on-chain, instantly issuing stablecoins or digital fiat directly to verified wallets. This architectural overhaul guarantees absolute data integrity, as altering historical records on a distributed ledger requires conquering a majority of network nodes—an economically unfeasible endeavor that renders fraud virtually impossible.
Biometric Authentication Evolution in Consumer Credit Markets
Biometric security frameworks are transitioning from rudimentary fingerprint scans on mobile devices to continuous, passive behavioral analysis. Over the coming decade, consumer credit markets will integrate multi-modal verification vectors that monitor unique physiological interactions, such as keystroke dynamics, gait analysis, and cardiovascular signature recognition through wearable tech. Real-life deployments of behavioral biometrics by institutions like HSBC demonstrate how continuous background authentication can thwart sophisticated account takeover attempts without disrupting the user experience.
By measuring how a borrower interacts with their device during the loan application process, lenders establish an unforgeable digital signature that persists throughout the entire lifecycle of the credit agreement, ensuring that the person who initiated the loan is the exact same individual managing the repayment schedule.
Legislative frameworks governing cross-border remote financial transactions must adapt to this borderless technological reality to prevent regulatory fragmentation. Global standard-setting bodies, such as the Financial Action Task Force, are actively drafting harmonization protocols to bridge disparate national compliance mandates regarding digital signatures and remote KYC processes. The European Union’s revised electronic identification and trust services framework serves as a prime real-world blueprint, establishing mutual recognition of digital credentials across member states.
Future legislative updates will likely mandate interoperable cryptographic standards, allowing a borrower in Singapore to execute a legally binding mortgage with a European lending institution seamlessly, provided both jurisdictions recognize mutually assured cryptographic proofs on a shared compliance network.
Understanding the trajectory of automated financial ecosystems requires a comprehensive examination of the technological milestones, adoption curves, regulatory hurdles, and security enhancements anticipated through the year 2035.
| Technological Milestones | Adoption Rates | Regulatory Hurdles | Security Enhancements |
|---|---|---|---|
| Autonomous smart contract loan origination | 25% by 2028 | Cross-jurisdictional legal enforceability | Zero-knowledge proof identity masking |
| Decentralized identity sovereign networks | 50% by 2031 | Data residency and privacy compliance | Quantum-resistant ledger encryption |
| Fully autonomous algorithmic credit scoring | 85% by 2035 | Algorithmic bias and transparency mandates | Continuous behavioral biometric monitoring |
The ultimate convergence of decentralized ledgers and autonomous smart contracts will transform credit from a burdensome administrative process into an instantaneous, invisible utility of global commerce.
Conclusion

Source: medium.com
Stepping boldly into this vibrant era of digital finance transforms an often stressful bureaucratic hurdle into an inspiring celebration of modern capability. By harnessing advanced cryptographic layers and seamless remote validation tools, we unlock a frictionless pathway toward homeownership, proving that brilliant innovation can successfully harmonize ultimate security with absolute human convenience for a brighter financial tomorrow.
