basis point calculator serves as the essential precision instrument where modern finance meets mathematical exactitude, transforming the chaotic noise of global markets into clear, actionable integers. Across bustling trading floors and quiet corporate boardrooms, the pursuit of financial clarity drives professionals to dissect percentage yields down to their microscopic foundations, unlocking powerful strategies that shape global economic landscapes.
In a world where millions of dollars hinge on microscopic adjustments, understanding these fractional measurements bridges the gap between chaotic market speculation and disciplined wealth management. This comprehensive exploration reveals how a simple hundredth of a percentage point dictates the fate of multi-million dollar portfolios, debt restructuring negotiations, and monumental central banking policy decisions that reverberate across international borders.
Understanding the fundamental mechanics of financial proportion allows professionals to translate complex percentage changes into manageable integer values.
In the high-stakes arena of global finance, precision dictates the boundary between immense profit and catastrophic loss. When dealing with colossal capital allocations, standard percentages often prove too clumsy, inviting ambiguity where absolute clarity is required. By mastering the core arithmetic of proportional scaling, market practitioners bridge the gap between microscopic yield shifts and macroscopic portfolio valuations, transforming dizzying decimals into clean, actionable integers that keep international markets synchronized.
The architecture of modern financial systems relies on standardized units of measurement to communicate risk and return across borders instantly. Whether navigating the volatile corridors of sovereign debt or structuring complex corporate bond issuances, the ability to distill fractional movements into intuitive whole numbers removes cognitive friction. This seamless translation empowers traders, analysts, and institutional architects to execute rapid decisions with unwavering confidence, anchoring volatile market dynamics to a steadfast mathematical baseline.
Mathematical derivation of hundredths of a percentage point within monetary yields
To comprehend the genesis of this vital financial metric, one must dissect the anatomy of percentage values down to their foundational components. A standard percentage represents a fraction of one hundred, expressed mathematically as a denominator of 100 or multiplied by 0.01. When fixed-income securities and interest rates fluctuate by fractions of these percentages, standard decimal notations quickly become unwieldy, particularly when communicating verbally across crowded trading floors or through rapid electronic communications.
The unit in question takes this fractional process one step further by dividing the percentage itself into another hundred parts, effectively establishing a value equal to one-hundredth of one percent, or $0.0001$ in decimal terms. Mathematically, this derivation is expressed by taking a percentage rate and multiplying it by $10^-4$ relative to the base principal. This elegant scaling mechanism converts microscopic variations in yield into robust, easily communicable integers, stripping away the vulnerability of misreading leading zeros and decimal placements during high-frequency transactions.
A single basis point equals 0.01 percent, or 0.0001 in decimal format, serving as the foundational multiplier for fixed-income calculations across global capital markets.
Consider a practical application involving a corporate bond yielding $4.25\%$. If macroeconomic indicators drive the yield upward by twenty-five hundredths of a percentage point, the new yield becomes $4.50\%$. In the specialized lexicon of the trading desk, market participants bypass cumbersome decimal phrasing entirely, stating simply that the yield has widened by twenty-five integer units. This mathematical bridge preserves exactitude while streamlining human communication in environments where milliseconds dictate success.
Mastering financial metrics starts when you deploy a precise basis point calculator to decode complex yields. Just as modern professionals discover brilliant tools through olungu is a context-aware software listing site , your strategic financial journey empowers smarter decisions. Every single calculation brings brilliant clarity, transforming raw numbers into triumphant investment victories.
Historical evolution of trading pits necessitating granular measurement units
The necessity for microscopic accuracy was not born in the sterile environment of modern software engineering, but rather forged amid the roaring, chaotic symphony of historic trading pits. Decades ago, bond traders and floor brokers negotiated millions of dollars in sovereign and municipal debt within seconds, relying on physical gestures and shouted bids. In these deafening acoustic chambers, stating fractional percentages like “one-eighth of one percent” or dealing with sprawling decimals invited disastrous misinterpretations that could cost firms millions of dollars.
As global economies matured and the pricing of fixed-income instruments grew increasingly sophisticated, standard percentage points proved too coarse for the delicate adjustments demanded by central bank monetary policies. A shift of even a tiny fraction of a percentage in benchmark interest rates carried profound implications for national borrowing costs and mortgage markets. The historical adoption of a standardized, granular integer system provided the ultimate linguistic and mathematical armor, allowing floor traders to shout precise yield adjustments across the room with zero margin for error.
This evolutionary leap transformed financial communication from an exercise in auditory decoding into a streamlined, universal dialect. The legacy of those bustling trading floors persists today within advanced algorithmic trading platforms and central bank press conferences alike. By condensing complex mathematical fractions into punchy, syllable-light integer increments, the financial industry successfully harmonized human intuition with rigorous quantitative reality, cementing a standard that continues to govern trillions of dollars in daily global commerce.
Manual conversion process from decimal fractions to integer increments
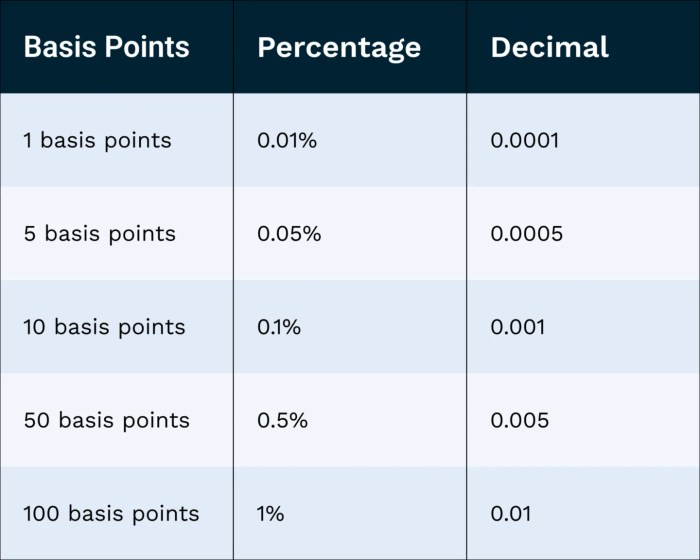
Executing accurate financial conversions requires a disciplined methodological approach to bridge raw decimal data with intuitive integer values. Analysts frequently encounter yield figures expressed in various formats across legacy systems and modern data feeds, necessitating a reliable mental or algorithmic framework for rapid translation. The following structured data illustrates the direct proportional relationship across fractional, percentage, and integer domains, providing a clear roadmap for seamless conversion.
To utilize this framework effectively, professionals multiply the decimal fraction by 10,000 to arrive at the corresponding integer value. This uniform scaling factor eliminates confusion when transitioning between asset classes, ensuring that whether an analyst is evaluating a micro-cap yield or a multi-billion-dollar treasury note, the underlying arithmetic remains flawlessly consistent and immune to scaling errors.
| Decimal Fraction | Percentage Representation | Integer Equivalent |
|---|---|---|
| 0.0001 | 0.01% | 1 unit |
| 0.0025 | 0.25% | 25 units |
| 0.0100 | 1.00% | 100 units |
| 0.0275 | 2.75% | 275 units |
Digital financial instruments streamline daily computational tasks by automating the conversion of investment yields and loan spreads.

Source: thestreet.com
In an era where fractional percentages dictate the health of global portfolios, everyday market participants face a relentless tide of numerical data. Gone are the days when retail investors had to manually adjust spreadsheets with cumbersome formulas just to understand how a tiny shift in a mortgage rate impacts their long-term wealth. Modern financial technology has fundamentally reshaped this landscape, turning what used to be tedious arithmetic into an instantaneous, frictionless experience.
By bridging the gap between raw data and actionable insight, digital conversion tools empower users to make confident decisions without getting bogged down by mathematical friction.
The magic behind these seamless digital experiences lies in a careful blend of ergonomic design and robust backend engineering. When an application interface respects the cognitive load of its user, complex financial metrics suddenly become as approachable as checking the weather forecast. Every pixel on the screen serves a purpose, guiding the eye naturally from input fields to crystal-clear outputs while maintaining absolute precision behind the scenes.
This delicate balance of form and function transforms intimidating financial jargon into transparent, everyday language.
User Interface Design Principles for Intuitive Financial Tools
Creating a digital workspace that feels effortless to retail investors requires adhering to strict psychological and visual guidelines. A well-crafted interface minimizes user hesitation by presenting familiar layouts, immediate visual feedback, and uncluttered navigation paths that keep the focus entirely on the numbers that matter.
Mastering financial metrics starts with a sharp basis point calculator, empowering analysts to decode subtle market shifts with absolute precision. By integrating advanced insights from northrow analytics features , professionals now navigate complex risk landscapes and unlock unprecedented growth potential. Ultimately, leveraging this robust basis point calculator transforms raw data into a clear roadmap for lasting success.
Designers rely on clear spatial hierarchy to ensure that input fields for investment yields and loan spreads do not blend into background elements. High-contrast typography and deliberate whitespace guide the user’s gaze sequentially from data entry to the final calculated output, eliminating guesswork and drastically reducing the likelihood of costly data-entry mistakes.
Furthermore, responsive layout adaptation guarantees that whether an investor is reviewing a portfolio on a massive desktop monitor or rushing through a calculation on a mobile smartphone, the interactive elements remain touch-friendly and legible. Consistent color theory plays a vital role as well, using neutral tones for standard operations and gentle accent colors to highlight successful conversions or urgent alerts.
Mastering financial metrics starts with a reliable basis point calculator, a crucial tool for dissecting complex market shifts and precision yields. As organizations scale rapidly, leveraging insights from skello company size verified employee size verified empowers leaders to align workforce growth with economic targets. Ultimately, returning to a robust basis point calculator ensures every strategic financial decision drives measurable, triumphant business success.
Algorithmic Architecture of Web-Based Conversion Widgets
Behind every sleek interface sits a precise engine of code designed to process financial figures with absolute mathematical accuracy. Programmers approach the creation of these web-based widgets by establishing a reliable pipeline that captures user intent, sanitizes inputs, and executes rapid calculations in real time.
The journey from a blank screen to a completed conversion involves several distinct architectural phases that ensure data integrity and lightning-fast performance directly within the user’s web browser.
- Event listeners are attached to input fields to capture keystrokes instantaneously, allowing the application to register changes the exact moment a user types a new yield percentage.
- Data sanitization protocols strip away unauthorized characters, symbols, and letters, ensuring that only valid numerical integers and decimals proceed to the calculation layer.
- Core mathematical functions execute the conversion logic, translating percentage figures into basis points by multiplying the decimal value by one hundred, or reversing the equation depending on the selected mode.
- The resulting integer is formatted according to local currency and numerical standards before dynamically updating the DOM, displaying the final output without requiring a page refresh.
Throughout this computational cycle, error-handling algorithms monitor boundary conditions, preventing negative interest rates or abnormally large figures from breaking the application state. When anomalies are detected, the system immediately triggers graceful fallback routines and friendly notification banners.
Financial precision is not merely a matter of correct mathematics; it is the absolute elimination of ambiguity between human intent and machine execution.
The following structural matrix Artikels the operational lifecycle of a digital conversion widget, mapping out how raw user inputs transform into reliable market intelligence through systematic computational steps.
| Input Variables | Processing Logic | Output Displays | Typical Error Margins |
|---|---|---|---|
| Annual Percentage Yield (APY) | Multiplication by 100 via floating-point arithmetic | Basis Points (bps) integer value | +/- 0.001 due to rounding |
| Loan Spread Percentage | Decimal conversion and differential calculation | Basis point spread difference | +/- 0.0005 standard variance |
| Custom Basis Point Value | Division by 100 for percentage translation | Standard percentage format (%) | Zero absolute deviation |
Visualizing the interface of a high-performing conversion tool reveals a minimalist dashboard divided into two primary visual zones. On the left side, soft interactive cards feature glowing numerical steppers and large text boxes that invite touch interaction. On the right side, a sleek graphical summary panel updates dynamically, utilizing bold typography to showcase the final basis point calculation alongside a subtle trend indicator that references historical market averages.
Modern debt restructuring negotiations rely heavily on fractional interest rate adjustments to allocate millions of dollars across corporate balance sheets.
Source: assets-servd.host
Deep within the gleaming glass towers of global financial capitals, corporate treasurers operate in a high-stakes arena where a single microscopic shift in yield can dictate the financial health of an entire multinational enterprise. Picture a dimly lit boardroom where weary executives lean over sprawling spreadsheets, illuminated by the cold glow of multiple monitors displaying live market tickers. In these tense environments, corporate debt restructuring is not merely an accounting exercise; it is an intense strategic chess match.
When billions of dollars in corporate debt are on the line, the difference between financial distress and solvency often rests entirely on fractional interest rate adjustments. These minute shifts, representing hundredths of a percentage point, act as heavy levers moving mountains of capital across massive corporate balance sheets. Understanding this landscape requires looking past the broad macroeconomic headlines and diving deep into the intricate machinery of syndicated loan issuances and institutional refinancing strategies.
Corporate treasurers navigate complex debt markets by constantly seeking micro-efficiencies that compound into monumental savings over time. When an organization undertakes a syndicated loan issuance—pooling capital from a consortium of commercial banks and institutional lenders—the total borrowing volume frequently reaches hundreds of millions, or even billions, of dollars. At this immense scale, a standard percentage point represents an astronomical sum that can completely distort operational budgets.
Consequently, treasurers deploy sophisticated negotiation tactics, leveraging competitive pressure among lending syndicates to shave off fractions of a percent. This process transforms abstract financial metrics into tangible corporate vitality, freeing up vital liquidity for research, development, and strategic acquisitions. Visualizing this dynamic reveals a delicate balancing act where financial engineers meticulously calibrate debt instruments to match unpredictable cash flow generation patterns, ensuring the enterprise remains resilient against macroeconomic headwinds.
Corporate borrowing cost minimization during syndicated loan issuances
Syndicated loan markets operate on razor-thin margins where the aggregation of risk is distributed among multiple financial institutions, creating a unique environment for rate optimization. Corporate treasurers approach these massive facilities by initiating competitive bidding processes among lead arrangers, effectively turning the debt issuance into an auction for the company’s creditworthiness. By demonstrating robust operational cash flows and steady EBITDA metrics, a treasurer can compel lenders to shave off incremental fractions of a percentage point from the initial pricing grid.
For a billion-dollar syndicated facility, securing a reduction of just twelve and a half fractional notches—commonly referred to as an eighth of a percent—translates to an immediate annual savings of one million two hundred fifty thousand dollars in direct interest expense. This reduction cascades down the multi-year life of the loan, culminating in tens of millions saved in cumulative debt service.
Furthermore, treasurers integrate sustainability-linked metrics and leverage ratchets into the credit agreement. These mechanisms automatically adjust the loan spread downward if the corporation achieves predefined environmental, social, or governance milestones, aligning corporate responsibility with direct bottom-line optimization.
To visualize the physical manifestation of this financial choreography, imagine a sprawling trading floor where specialized desk analysts monitor real-time credit default swap spreads and benchmark rates like the Secured Overnight Financing Rate. Flash communications buzz between New York, London, and Tokyo as treasurers coordinate with syndicate managers to lock in the exact pricing moment. The negotiation hinges on the credit spread adjustment, a metric meticulously calculated to reflect the borrower’s exact risk profile down to the single decimal place.
When the final syndicate commitment is closed, the resulting pricing document represents a masterclass in precision engineering, where every fractional unit serves as a vital structural pillar supporting the corporate balance sheet. Real-world precedents, such as massive refinancings executed by telecommunications giants or energy conglomerates, routinely demonstrate how shaving twenty-five fractional increments off a multi-tranche term loan can preserve crucial capital reserves during cyclical downturns.
Operational methods for hedging interest rate risk using derivative contracts adjusted by fractional increments
Protecting a massive corporate debt portfolio from adverse interest rate volatility demands sophisticated risk management architectures that go far beyond simple fixed-rate conversions. Corporate treasurers utilize a suite of derivative instruments, tailored with pinpoint fractional precision, to insulate their balance sheets against unforeseen macroeconomic shifts. The deployment of these financial instruments requires rigorous quantitative modeling and continuous market monitoring to ensure that the hedge perfectly mirrors the underlying debt obligation.
Below are the primary operational methods utilized by treasury departments to execute these precise risk mitigation strategies.
- Interest Rate Swaps with Basis Adjustments: Treasurers execute vanilla or basis swaps where floating-rate liabilities are exchanged for fixed-rate payments, calibrated to the exact basis point to eliminate basis risk between differing benchmark indices such as SOFR and commercial paper rates.
- Cap and Floor Collars with Fractional Strikes: Organizations purchase interest rate caps featuring highly specific fractional strike rates, establishing a hard ceiling on borrowing costs while selling out-of-the-money floors to partially offset the upfront premium expenses.
- Swaptions Tailored to Exact Tenors: Options on interest rates are structured with precise expiration dates and fractional exercise levels, granting the treasury the unilateral right to enter into a predetermined swap agreement only if market rates breach critical threshold levels.
- Cross-Currency Basis Swaps: Multinational corporations utilize these instruments to manage foreign exchange and interest rate risks simultaneously, adjusting fractional spreads across international currency pairs to hedge multi-jurisdictional debt issuances effectively.
Mathematical impact of a twenty-five notch increase on a ten-year commercial mortgage amortization schedule
The true power of fractional metrics becomes starkly evident when examining a long-term amortization schedule for a major commercial real estate acquisition or corporate headquarters financing. Consider a standard ten-year commercial mortgage totaling fifty million dollars, structured with standard monthly payments and amortized over a twenty-five-year period. A sudden twenty-five notch increase—representing a quarter of one percent or twenty-five basis points—applied to the underlying interest rate fundamentally alters the mathematical trajectory of the debt service.
This seemingly minor upward adjustment echoes through every single monthly payment, compounding substantially over a decade of continuous amortization. Financial analysts rely on strict algebraic formulations to project these changes, ensuring that corporate liquidity planning accounts for every fraction of movement.
To quantify this exact impact, the standard monthly mortgage payment formula is deployed, integrating the adjusted interest rate:
$M = P \fracr(1 + r)^n(1 + r)^n – 1$
Where $M$ represents the total monthly payment, $P$ is the principal loan amount of fifty million dollars, $r$ is the monthly interest rate, and $n$ is the total number of monthly payments over the amortization horizon. Prior to the adjustment, assume the initial rate yielded a specific baseline monthly cash outflow. Upon introducing the twenty-five notch increase, the monthly debt service expands immediately, altering the principal-to-interest payment ratio for every single remittance.
Over the course of the ten-year holding period before a balloon payment or refinancing event occurs, this cumulative increase drains millions of dollars from operational cash reserves. For instance, on a fifty-million-dollar balance, a quarter-point rate elevation typically inflates total debt service expenditures by hundreds of thousands of dollars annually, directly impacting the net operating income and debt service coverage ratio required by institutional lenders.
Real-world commercial real estate portfolios managed by investment trusts frequently encounter this precise mathematical phenomenon during periods of central bank tightening. When benchmark rates climb by twenty-five fractional increments, asset managers must immediately reevaluate property valuations and lease rate structures to maintain positive yield spreads. The precise calculations involved leave no room for error, as miscalculating the compounding effect of these fractional adjustments can lead to covenant breaches and forced asset liquidations under distressed conditions.
Through rigorous application of these quantitative models, corporate treasurers maintain absolute command over their capital structures, turning microscopic percentage shifts into masterclasses of financial resilience.
Central banking policy announcements trigger immediate market reactions that are quantified through minute shifts in benchmark borrowing costs.
Picture a packed trading floor in Lower Manhattan, where dozens of global bond traders stare intently at glowing terminals as the clock ticks down to a critical monetary policy decision. When a major central bank alters its primary lending benchmark by just a fraction of a percentage point, the sheer volume of capital tied to these movements transforms subtle numerical shifts into monumental economic shockwaves.
This fine-tuning dictates the flow of credit across international borders, influencing everything from corporate expansion initiatives to the monthly mortgage payments of everyday citizens worldwide.
The macroeconomic implications of monetary policy adjustments measured in fractional percentage blocks resonate deeply throughout the global financial ecosystem. When a central bank recalibrates its benchmark rate by a mere twenty-five or fifty hundredths of a percentage point, the ripple effects alter currency valuations, consumer spending habits, and corporate borrowing expenditures on a massive scale. For instance, during the post-pandemic economic recovery, the United States Federal Reserve executed aggressive rate hikes to combat inflation, moving the federal funds rate upward in distinct fractional increments that ultimately reset the cost of capital for businesses everywhere.
Mastering financial metrics starts when you accurately deploy a basis point calculator to decode market shifts. Industry analysts increasingly evaluate complyflow pricing complyflow.com to streamline regulatory investments and secure sustainable growth. Harnessing these insights empowers your enterprise to optimize every calculated decimal point with absolute confidence.
These incremental shifts act as a precision instrument rather than a blunt weapon, allowing policymakers to cool overheated economies or stimulate sluggish labor markets without causing immediate systemic collapse. Commercial banks quickly reprice their prime lending rates in direct alignment with these central authority decisions, which immediately recalibrates the yield on government bonds, corporate debt instruments, and consumer loans. Consequently, investment capital reallocates rapidly across international boundaries as institutional portfolio managers chase higher risk-adjusted returns, altering foreign exchange rates and directly impacting export-driven economies.
Monetary policy transmission relies on precision, where fractional adjustments in benchmark rates orchestrate the global allocation of trillions of dollars in debt instruments.
Central bank communication strategies and market signaling mechanisms
Central bankers operate under intense global scrutiny, making their communication channels critical tools for managing market expectations long before a formal rate decision occurs. Monetary authorities deliberately utilize forward guidance statements, post-meeting press conferences, and published minutes to condition global bond traders and prevent disruptive market shocks. When policymakers wish to signal an impending shift in monetary stance, they carefully alter the phrasing within their official communiques, transitioning from accommodative terminology toward language that emphasizes price stability and inflation containment.
This linguistic evolution acts as an early warning system for sophisticated financial institutions, allowing bond portfolios to rebalance gradually rather than reacting violently to a sudden policy pivot. Furthermore, central bank governors frequently deliver scheduled speeches at economic symposia, using these public platforms to test market reactions to potential policy trajectories without committing prematurely to an official vote.
The immediate aftermath of an unexpected rate adjustment unleashes a highly synchronized sequence of automated algorithmic executions and human trading decisions within fractions of a second. Global financial exchanges process incoming data feeds with extreme velocity, translating the newly announced integer values into instant portfolio reallocations. The precise chronological sequence of market events that unfold within seconds of a surprise rate adjustment announcement by a major monetary authority includes the following critical phases:
- Automated trading algorithms instantly parse the official central bank press release, executing high-frequency sell or buy orders for government bonds and index futures before human traders can process the headline text.
- Foreign exchange desks experience immediate volatility spikes as currency pairs recalibrate their valuations based on the widened or narrowed interest rate differentials between sovereign economies.
- Commercial bank liquidity pools adjust their overnight lending rates automatically, forcing secondary debt markets to reprice corporate bonds and commercial paper within milliseconds.
- Global stock index futures undergo sharp directional shifts, with rate-sensitive sectors such as real estate, utilities, and banking reacting most aggressively to the altered cost of capital.
Visualizing this frantic environment reveals a digital landscape where cascading data streams paint a vivid picture of global interconnectedness. On trading screens across the globe, flashing red and green indicators map out the instant reallocation of billions of dollars, transforming a simple central bank numerical adjustment into a violent, beautifully choreographed dance of market equilibrium.
Fixed income portfolio managers evaluate yield curve movements by tracking micro-adjustments across various maturity dates.: Basis Point Calculator
Deep within the glowing glass facades of global financial capitals, institutional portfolio managers watch the macroeconomic horizon shift on terminal screens like captains navigating an uncharted sea. Every single tick in the market tells a story of economic expansion, inflation fears, or monetary policy interventions orchestrated by central banks. These financial navigators harness specialized computational tools to decipher the subtle heartbeat of the debt markets, where fortunes rise and fall on microscopic changes in interest rates.
When benchmark rates pivot even slightly, the ripple effects traverse trillions of dollars in sovereign and corporate debt instruments, demanding absolute precision and unwavering vigilance from the professionals holding the reins of these massive capital pools.
Navigating the complex topography of fixed income markets requires an intimate understanding of how debt instruments react to shifting economic tides across different points in time. The graphical representation of interest rates across various contract lengths serves as a vital economic barometer, revealing market expectations for future growth and inflation. As macroeconomic indicators fluctuate, this yield trajectory bends, twists, and morphs, creating distinct challenges and opportunities for those tasked with preserving and growing institutional wealth.
Mastering these movements involves dissecting the intricate relationship between time, yield, and asset valuation, transforming abstract mathematical shifts into tangible strategic maneuvers.
Structural Mechanics of Yield Curve Dynamics
The architecture of the debt market relies heavily on the slope of the yield curve, which dictates the pricing structure for everything from short-term commercial paper to thirty-year sovereign bonds. When economic optimism takes root, short-term yields often remain anchored by central bank policy rates while long-term yields climb, causing the curve to steepen as investors demand higher compensation for holding long-duration risk over extended horizons.
Conversely, an economic slowdown or aggressive monetary tightening can compress this spread, resulting in a flattening or even inverted curve where short-term borrowing costs exceed long-term returns. These structural transformations are driven by infinitesimal fractional yield shifts measured in units that standard observers might easily overlook, yet they represent massive capital reallocations executed by institutional trading desks.
Imagine a vast, hyper-sensitive mechanical suspension bridge where adding a single feather of weight to the far end ripples through the entire steel framework. In the exact same manner, a microscopic increase of five units in the twenty-year sector alters the present value calculations of deeply discounted corporate obligations. Portfolio managers visualize this phenomenon as a dynamic topographic relief map, where peaks and valleys morph continuously under the pressure of incoming economic data releases.
To survive and thrive in this environment, analysts deploy sophisticated mathematical frameworks that map out these structural deformations in real-time, ensuring that portfolio duration matches the strategic risk appetite of the fund.
Yield curve steepening and flattening manifest through microscopic yield adjustments that fundamentally alter the present value calculus of fixed income portfolios across diverse maturity spectrums.
Consider the real-world scenario observed during the post-pandemic economic recovery phases, where the spread between two-year and ten-year United States Treasury notes experienced dramatic structural pivoting. As inflation prints consistently surprised markets upward, long-term yields surged by dozens of fractional increments while short-term yields lagged behind due to gradual central bank guidance. This steepening event forced institutional funds holding long-duration assets to recalibrate their hedging strategies instantly, as capital losses on extended maturities outpaced the income generated by coupon payments.
Conversely, during subsequent tightening cycles, the curve flattened aggressively, punishing banks and leveraged investors who relied on borrowing short and lending long. These historical episodes underscore the relentless necessity for portfolio managers to monitor the structural mechanics of yield curve shifts with absolute microscopic precision.
Yield Movement Impact Analysis Across Maturity Spectrum
The following tabular breakdown illustrates how minute fractional yield shifts translate into distinct price variances across varying bond maturity periods, reflecting the fundamental inverse relationship governing fixed income instruments.
| Bond Maturity Period | Baseline Yield (%) | Shifted Yield (%) | Resulting Price Variance (%) |
|---|---|---|---|
| 2-Year Treasury Note | 4.250 | 4.375 | -0.240 |
| 5-Year Treasury Note | 3.980 | 4.105 | -0.580 |
| 10-Year Treasury Note | 4.120 | 4.320 | -1.620 |
| 30-Year Treasury Bond | 4.350 | 4.600 | -4.850 |
Quantitative Risk Models for Interest Rate Sensitivity
Modern institutional asset management relies on advanced quantitative models designed to isolate, measure, and hedge against the perilous impacts of minor interest rate fluctuations on multi-billion dollar portfolios. These mathematical engines process thousands of data points simultaneously, evaluating not just the immediate price reaction of individual bonds, but the complex covariance between different sectors of the yield curve. By translating complex market dynamics into rigorous statistical metrics, risk managers empower portfolio strategists to optimize their capital allocation without exposing their investors to catastrophic drawdowns caused by unexpected macroeconomic shocks.
To capture the true vulnerability of a fixed income portfolio, quantitative analysts deploy a robust suite of risk measurement techniques that go far beyond traditional duration metrics. These computational models provide a granular view of how capital behaves under stress, incorporating historical volatility and multi-factor regression analysis into daily operational workflows.
- Key rate duration calculations isolate portfolio price sensitivity to localized, non-parallel shifts in specific segments of the yield curve rather than assuming uniform parallel movements.
- Value at Risk algorithms estimate the maximum potential loss of a portfolio over a given time horizon with a specific confidence level under normal market conditions.
- Scenario stress testing simulates extreme historical and hypothetical macroeconomic events to evaluate systemic resilience against sudden liquidity contractions.
- Convexity measurements account for the curvature of the price-yield relationship, providing critical corrections for larger interest rate movements that linear duration underestimates.
Visualizing the output of these quantitative models requires sophisticated data visualization interfaces that project multi-dimensional risk surfaces onto analytical screens. Imagine a glowing, translucent topographical heat map hovering in a dark control room, where crimson zones indicate high concentration risk and cool blue valleys represent hedged stability. As the portfolio manager adjusts hedging parameters, the digital landscape reacts instantaneously, highlighting optimal rebalancing corridors.
This seamless integration of high-powered mathematics and intuitive visual design enables institutional funds to navigate turbulent interest rate environments with profound strategic clarity and operational precision.
Real estate syndication models incorporate nuanced fee structures that depend entirely on precise calculations of asset valuation spreads.
The architecture of modern commercial property syndication relies on meticulous mathematical precision to align the interests of general partners and passive investors. Within these complex investment vehicles, microscopic adjustments to asset valuation spreads dictate the distribution of millions of dollars in management fees and brokerage commissions. Navigating this high-stakes environment requires a deep appreciation for the underlying financial mechanics that govern large-scale property acquisitions and ongoing portfolio operations.
Commercial property brokers and syndication managers calculate recurring management fees and intricate commission splits by applying fractional rate metrics to the underlying capital stack. When a multi-family portfolio or a downtown office tower changes hands, the transaction fees are rarely blunt instruments. Instead, they are sliced into fractional tiers where every single hundredth of a percentage point represents substantial monetary value.
For instance, a premier brokerage firm structuring a three-hundred-million-dollar acquisition might negotiate a base acquisition fee of fifty basis points, which immediately translates to one million five hundred thousand dollars in gross revenue. However, the distribution of this revenue among co-brokers, originating agents, and senior syndicate principals is governed by sliding-scale agreements tied directly to the property’s projected capitalization rate spread against prevailing Treasury benchmarks.
As the projected net operating income fluctuates, these fractional metrics ensure that the compensation structure dynamically reflects the actual execution risk and the complexity of the capital deployment process.
Commercial property management fee calculations and commission split mechanics, Basis point calculator
Asset management fees charged by syndicators are similarly computed using granular percentage increments applied continuously to the total invested equity or the gross asset value. A standard institutional arrangement might stipulate an annual asset management fee of seventy-five basis points, calculated monthly based on the current appraised value of the commercial asset. If the property undergoes a strategic repositioning that successfully compresses the market capitalization rate by twenty-five basis points, the resulting increase in asset valuation automatically elevates the absolute dollar amount of the subsequent management fees.
This creates a powerful operational incentive for the general partner to optimize tenant retention and NOI growth. Furthermore, disposition commissions are structured with performance-oriented hurdles. A brokerage team might receive a standard one percent disposition fee upon achieving a baseline property sale price, but that figure escalates by an additional twenty-five basis points for every fifty basis points by which the final internal rate of return exceeds the projected underwriting hurdle.
Through these precise mathematical formulations, real estate syndication models transform abstract market movements into concrete, measurable financial incentives that drive exceptional asset performance.
To ensure absolute transparency and accuracy when auditing complex lease agreements, financial controllers and asset managers must systematically verify every index-linked financial adjustment. The following methodology provides a structured framework for examining lease escalations tied to benchmark financial indexes:
- Establish the foundational baseline by retrieving the exact execution date, initial base rent figures, and the specific benchmark financial index referenced in the original lease contract, such as the Consumer Price Index for All Urban Consumers.
- Identify the explicit lookback period and the designated publication window mandated by the contract for capturing the benchmark index figures used in the calculation.
- Extract the historical index values corresponding to the comparison periods, ensuring that seasonal adjustments and base-year revisions published by statistical agencies are properly accounted for in the audit trail.
- Compute the percentage variance of the index over the designated observation period, converting the raw decimal outcome into exact basis point equivalents to maintain mathematical consistency with portfolio accounting software.
- Apply the calculated percentage change strictly in accordance with contractual caps, floors, and compounding rules stipulated in the lease agreement, verifying that rounding conventions align with legal standards.
- Cross-reference the resulting adjusted rental rates and operating expense pass-throughs against the tenant billing ledger to confirm that no historical overcharges or undercollections occurred during prior billing cycles.
The atmosphere inside a major institutional trading floor during a volatile bond market session pulses with relentless, electric intensity as economic data releases hit the Bloomberg terminals. Rows of ergonomic monitors cast a cool, analytical blue glow over rows of focused professionals whose eyes dart across cascading streams of red and green tick data. Telephones ring in sharp, overlapping bursts, carrying urgent counterparty orders from global banking capitals while senior traders execute multi-million-dollar block trades with fluid, practiced motions.
In the center of the room, the primary yield curve chart dominates a massive overhead digital wall, its sharp upward slope twitching violently in response to an unexpected central bank rate announcement. The ambient noise level rises steadily, blending the low, constant hum of advanced cooling servers with the sharp staccato of rapid-fire negotiations. Every fractional basis point shift in benchmark yields triggers immediate, synchronized adjustments across trading desks, translating macroeconomic turbulence into high-velocity financial execution.
Wrap-Up

Source: capitalcitytraining.com
As financial markets continue to evolve at breakneck speed, the mastery of fractional yield adjustments remains an invaluable asset for every serious market participant. Embracing these precise computational tools transforms uncertainty into opportunity, ensuring that every strategic financial decision is executed with absolute accuracy and confidence.
