skills needed for accounting represent a profound professional evolution, shifting far beyond traditional ledger entries into a dynamic landscape of automated precision, strategic foresight, and global compliance mastery. Across glass-walled corporate towers and fast-paced digital hubs, modern financial stewards are rewriting the playbook, transforming raw numbers into glowing beacons of sustainable enterprise growth and unwavering organizational resilience.
Today’s financial experts stand at the intersection of technological innovation and strategic leadership, wielding advanced cloud platforms, predictive forecasting models, and rigorous forensic algorithms to safeguard corporate futures. As global markets fluctuate and regulatory frameworks grow increasingly complex, the modern practitioner must seamlessly blend analytical rigor with visionary storytelling, turning intricate balance sheets and ESG metrics into actionable roadmaps that guide executive boardrooms toward lasting prosperity.
Modern financial professionals must master the digital transformation of ledger systems through advanced automation
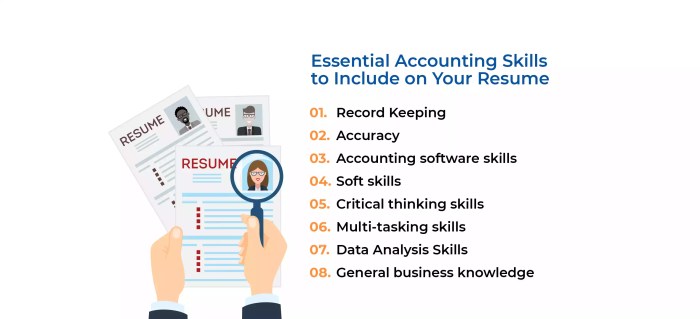
Source: edoxi.com
Mastering sharp analytical expertise and meticulous financial tracking opens doors to incredible career heights, much like evaluating the precise cost of starlight mini cloud processing in topaz video empowers creators to optimize their brilliant digital workflows. Embracing these crucial competencies transforms complex data into clear visions, guiding modern enterprises toward ultimate success.
The landscape of corporate finance has undergone a seismic shift, pulling practitioners away from dusty paper ledgers and anchoring them firmly in the realm of high-speed digital infrastructure. Picture a cluttered room filled with towering filing cabinets, where accountants manually stamped receipts and spent countless hours balancing trial balances with green ink and physical calculators. That tangible, analog era has largely vanished, replaced by sophisticated cloud-integrated accounting architectures that pulse with real-time data across global networks.
Today’s accountants are no longer just historians of past transactions; they operate as forward-looking strategists who navigate complex cryptographic ledgers and automated data streams with the precision of air traffic controllers.
This evolutionary leap from physical paper to decentralized cloud ecosystems has redefined organizational agility, allowing leadership teams to access comprehensive financial statements from any corner of the globe within milliseconds. The transition required immense technical adaptation, pushing professionals to abandon traditional desktop installations in favor of dynamic platforms that update instantaneously. As companies scale, their financial architectures must expand synchronously without incurring prohibitive hardware costs, a feat made possible only through the robust capabilities of modern cloud-hosted financial infrastructure.
Evolution from Manual Paper Ledgers to Cloud Architectures
The journey of corporate record-keeping began in ancient merchant ledgers and evolved through stationary desktop computers that stored data locally on fragile hard drives. Physical ledgers were notoriously vulnerable to physical disasters, human error, and the slow creep of inefficiencies that delayed month-end closes by weeks. The advent of enterprise resource planning systems brought localized digital databases, yet these silos still required manual data entry and cumbersome file transfers via physical drives or local area networks.
The ultimate paradigm shift arrived with cloud-integrated architectures, where encrypted financial data streams reside in secure, multi-tenant server environments. Organizations like enterprise software giants and modern fintech firms have proven that transitioning to these environments slashes infrastructure overhead while providing an immutable audit trail that satisfies stringent regulatory frameworks across international jurisdictions.
Robotic Process Automation in Daily Bookkeeping Workflows
Robotic process automation acts as an invisible, tireless workforce that fundamentally reshapes daily bookkeeping by shouldering the crushing weight of repetitive, rule-based tasks. Imagine walking into the office while a fleet of software bots has already processed thousands of overnight transactions, matched vendor invoices against purchase orders, and flagged anomalies in employee expense reports before human eyes even review the dashboard.
These bots interact with legacy user interfaces, web portals, and modern APIs just like a human clerk, but they operate at lightning speed with a near-zero error rate. When routine data entry, bank reconciliations, and invoice generation are delegated to automated scripts, the entire rhythm of the accounting department shifts dramatically from reactive firefighting to proactive financial analysis. Bookkeepers no longer spend their mornings copy-pasting numbers from PDF invoices into general ledger software; instead, they oversee bot exception queues, investigating only the complex transactions that genuinely require human judgment and critical thinking.
This integration elevates the daily operational experience, turning mundane keystrokes into strategic oversight and allowing accounting professionals to dedicate their mental energy to cash flow forecasting, tax optimization, and advising business units on profitable growth trajectories.
True modernization in finance is not merely about abandoning paper; it is about empowering human intellect through relentless algorithmic efficiency.
Comparative Analysis of Legacy Desktop Software and Cloud Platforms
Evaluating the operational differences between traditional on-premise solutions and contemporary cloud environments reveals stark contrasts in capability, financial outlay, and collaborative potential for growing business entities.
| Evaluation Metric | Legacy Desktop Software | Cloud Platforms |
|---|---|---|
| Security Infrastructure | Vulnerable to local hardware theft, physical office disasters, and manual, inconsistent software patching routines. | Protected by enterprise-grade encryption, automated threat detection, and continuous geographical data redundancy. |
| Operational Speed | Limited by local computer processing power, manual data transport, and batch-processing limitations. | Powered by elastic cloud servers offering instantaneous calculations and real-time transaction syncing. |
| Financial Cost Model | High upfront capital expenditures for servers, perpetual software licenses, and dedicated IT maintenance staff. | Predictable operational expenditure via subscription models with zero hardware maintenance overhead. |
| Team Collaboration | Siloed data access restricted to local workstations or complex, unsecured virtual private network tunnels. | Seamless, simultaneous multi-user access across global teams with granular role-based permissions. |
Exact Procedures for Migrating Historical Financial Records Safely
Executing a seamless migration of historical financial records to a modern cloud ecosystem demands rigorous planning, meticulous data cleansing, and structured validation protocols to prevent catastrophic loss of organizational history. Financial institutions and corporate entities cannot afford discrepancies when transferring years of general ledger balances, accounts receivable, and asset depreciation schedules into a new digital ledger. The migration blueprint relies on a strict sequence of technical and operational safeguards that protect the integrity of the data throughout the transition phase.
- Conduct a comprehensive data audit of all existing legacy databases to identify duplicate entries, obsolete accounts, and corrupted transaction histories that should be archived rather than migrated.
- Establish a secure, encrypted staging environment where test extractions of historical ledgers can be mapped against the data schema requirements of the new cloud platform.
- Perform trial migration runs using representative subsets of the financial data to measure processing speed, verify field mapping accuracy, and test the integrity of historical trial balances.
- Execute a complete parallel-run accounting period where both the legacy system and the new cloud platform operate concurrently, verifying that automated calculations and manual adjustments yield identical financial reports.
- Lock the legacy system against further data entry once the parallel run is successfully verified, perform the final delta migration of transitional closing balances, and activate the cloud architecture as the primary system of record.
Strategic enterprise budgeting requires anticipating volatile global economic shifts before they impact profit margins.

Source: collidu.com
In today’s interconnected global marketplace, the margin for financial error shrinks with every macroeconomic tremor, forcing modern finance leaders to look far beyond historical trial balances. Yesterday’s static spreadsheet budgets have been entirely replaced by living, breathing financial blueprints capable of sensing geopolitical friction, currency turbulence, and supply chain disruptions before they ever touch the corporate income statement. Navigating this high-stakes arena demands an aggressive blend of foresight, algorithmic precision, and unyielding strategic discipline.
Quantitative forecasting models serve as the vital radar systems for the enterprise, scanning the horizon of global commerce to predict supply chain financial bottlenecks long before inventory shortages manifest in the ledger. By ingesting massive streams of historical throughput data, real-time logistics metrics, and macroeconomic indicators, these advanced algorithms simulate thousands of potential operational futures simultaneously. When a critical component manufacturer in Southeast Asia faces a localized labor strike or a sudden surge in regional energy costs, the predictive model instantly traces the ripple effects upstream and downstream.
It calculates the precise capital starvation points, revealing exact weeks where working capital will freeze due to delayed shipments and extended vendor payment cycles. For instance, global manufacturing giants harness these predictive analytics to anticipate raw material price spikes driven by trade policy shifts, enabling procurement divisions to lock in fixed-rate contracts and reallocate liquidity proactively, thereby shielding operating margins from sudden external shocks.
Corporate Cash Flow Resilience Under Inflationary Pressure
Protecting enterprise solvency when inflation runs hot requires a rigorous, systematic stress-testing methodology that pushes cash flow parameters to their absolute breaking points. Financial architects construct adverse multi-variable scenarios where input costs escalate by unexpected margins while customer payment behaviors simultaneously lengthen due to broader macroeconomic stress. By injecting these severe variables into the cash conversion cycle, leadership can observe the exact velocity at which liquid reserves evaporate over a rolling twelve-month horizon.
This systematic stress-testing exposes hidden vulnerabilities in inventory holding strategies and uncovers structural weaknesses in legacy pricing models that fail to transfer rising supplier costs to end consumers in a timely manner. Through this disciplined simulation exercise, corporate treasurers transition from reactive firefighting to commanding total liquidity control, ensuring the organization maintains a healthy runway even during prolonged periods of currency devaluation and compounding cost pressures.
Foreign exchange volatility remains a silent assassin of corporate profitability, capable of eroding double-digit earnings growth overnight through unhedged currency exposures. Implementing a structured risk mitigation framework is non-negotiable for multinational entities operating across fragmented monetary jurisdictions.
- Deploying multi-currency netting systems to naturally offset incoming receivables and outgoing payables in identical foreign denominations, thereby drastically minimizing transaction volume exposure.
- Executing layered hedging programs utilizing zero-cost collar options and forward contracts to lock in favorable exchange rates for projected capital expenditures over a rolling eight-quarter horizon.
- Establishing decentralized treasury centers equipped with localized liquidity buffers to absorb sudden devaluations in emerging market currencies without destabilizing the consolidated parent balance sheet.
- Enforcing dynamic pricing clauses in long-term international supply contracts that automatically adjust invoice totals based on predetermined foreign exchange rate fluctuation thresholds.
Visualizing the physical reality of these monetary defenses reveals a hyper-modern corporate treasury control room, where towering curved glass monitors display real-time global currency heat maps pulsing with crimson and emerald alert tiers. Automated data feeds stream continuous ticker updates from international central banks, while complex volatility curves intersect in three-dimensional holographic projections above sleek obsidian trading desks, mapping out corporate exposure zones across continents with absolute clarity.
Mathematical Frameworks for Capital Expenditure Allowances
Allocating capital efficiently demands mathematical rigor that accounts for the time value of money, probabilistic risk weighting, and the invisible friction of opportunity costs in dynamic markets. Modern financial engineers rely on sophisticated quantitative equations to evaluate the true economic value of long-term investments before a single dollar leaves the corporate vault. These frameworks ensure that every major capital project clears hurdles that reflect the true cost of capital under prevailing economic conditions.
Net Present Value equals the summation of expected cash inflows divided by one plus the weighted average cost of capital raised to the power of the period, minus the initial capital outlay.
To further refine these allowances, organizations integrate Real Options Analysis alongside traditional Discounted Cash Flow models to account for managerial flexibility in uncertain environments. This approach treats capital investments not as static, irreversible commitments, but as phased opportunities where management holds the explicit right to expand, contract, or abandon projects as market intelligence evolves. By quantifying the strategic value of operational flexibility, the mathematical framework prevents premature capital starvation during market downturns while greenlighting aggressive expansion the moment macroeconomic indicators signal a sustainable upward trajectory.
Mastering modern financial balancing demands sharp analytical abilities and profound mathematical precision. Today, ambitious professionals leverage advanced residential remodeling estimating software to conquer complex project budgets with absolute confidence. Embracing these innovative digital tools brilliantly enhances your core accounting expertise, unlocking fresh pathways toward ultimate career excellence and unstoppable workplace success.
Forensic auditing competencies protect organizational assets from sophisticated internal fraud schemes.

Source: theknowledgeacademy.com
In the quiet corners of corporate ledger rooms, invisible predators often operate with astonishing precision, siphoning wealth through meticulously concealed cracks in standard accounting controls. Modern business fortresses demand a specialized guardian who looks beyond routine balancing, diving deep into the digital and behavioral undercurrents of enterprise operations to safeguard corporate lifelines against calculated betrayal.
The landscape of white-collar crime has evolved beyond simple pocket-lining into complex digital larceny executed by trusted insiders who understand the exact contours of corporate oversight. Detecting these hidden fractures requires an acute blend of algorithmic vigilance and sharp human observation, transforming the forensic accountant from a historical scorekeeper into an active corporate defender.
Algorithmic detection of ledger anomalies
Modern financial vigilance relies heavily on advanced computational models to scan millions of data points instantly, catching the faint digital footprints left by internal perpetrators before substantial damage occurs. These algorithmic watchdogs transform vast oceans of transactional history into clear operational intelligence by continuously learning normal enterprise patterns and immediately flagging deviations that escape the human eye.
Anomaly detection algorithms operate by establishing a rigorous baseline of standard business behavior, analyzing historical variables such as transaction frequency, unusual timing, and vendor payment velocities. When an internal actor attempts to bypass authorization thresholds by splitting a large illicit invoice into multiple smaller payments just beneath the mandatory review limit, Benford’s Law algorithms instantly recognize the unnatural distribution of leading digits.
Machine learning classifiers continuously ingest multidimensional data, evaluating metadata like IP addresses, login timestamps, and device fingerprints associated with journal entry postings. If a mid-level accounting clerk suddenly initiates high-value wire transfers outside standard operating hours from an unrecognized terminal, the system flags the activity immediately, generating an instant high-priority alert for the forensic investigations team. Historical enterprise fraud cases, such as the massive accounting scandals uncovered at multinational firms over the past decade, heavily underscore the reality that automated anomaly detection dramatically reduces the dwell time of corporate embezzlement.
Constant algorithmic vigilance bridges the dangerous gap between hidden ledger manipulation and total corporate financial ruin.
Translating raw mathematical probabilities into actionable investigative leads requires structured operational protocols that eliminate advance warning, ensuring that physical evidence and digital trails remain entirely undisturbed.
Standard operating procedures for unannounced audits
Executing unannounced cash and inventory verifications demands absolute secrecy, precision, and unwavering adherence to established protocols to prevent perpetrators from hastily concealing discrepancies or destroying crucial physical evidence. The following sequential phases Artikel the mandatory steps forensic teams must execute during a surprise audit.
- The investigative team secures immediate control over all physical cash handling stations, petty cash boxes, and regional warehouse entry points simultaneously to prevent asset shifting between locations.
- Investigators freeze all active inventory management software terminals and physical ledger systems, restricting remote access privileges for all relevant accounting personnel until reconciliation is complete.
- Physical counts of physical stock and negotiable instruments are conducted by independent teams, cross-referencing physical quantities directly against perpetual inventory records and general ledger balances.
- Any observed variances, damaged goods logs, or unrecorded adjustments are immediately documented with photographic evidence and signed witness statements from independent floor supervisors.
Beyond physical verification of assets, forensic investigators must also decode the subtle human behavioral cues that routinely accompany the immense psychological pressure of ongoing corporate embezzlement.
Psychological indicators of corporate embezzlement
Long before digital anomalies appear on balance sheets or inventory counts fall short, individuals orchestrating sophisticated internal fraud schemes frequently exhibit distinct behavioral transformations driven by the immense stress of maintaining deception. Recognizing these psychological markers during routine interactions provides forensic professionals with invaluable early warnings regarding potential insider threats.
- Perpetrators frequently display extreme possessiveness over their specific job duties, aggressively resisting mandatory vacations, cross-training initiatives, or workload sharing arrangements that might expose their fraudulent methods to colleagues.
- Embezzlers often exhibit sudden, unexplained upgrades in lifestyle, displaying luxury assets, expensive vehicles, or lavish spending habits that clearly exceed their known compensation structure and legitimate personal financial means.
- A noticeable shift toward defensive hostility, hyper-sensitivity to casual questioning, or uncharacteristic irritation during routine internal audits often signals deep-seated anxiety about potential exposure.
- Fraudsters tend to display chronic workplace fatigue, restlessness, or visible anxiety, stemming from the exhausting daily mental burden required to perpetually balance falsified records and conceal discrepancies.
Structured classification frameworks offer clarity on how various fraud categories manifest and how they are systematically uncovered, contained, and resolved within enterprise environments.
Mastering modern accounting demands sharp analytical prowess and financial acumen. Professionals now transform complex spreadsheets into vivid insights using introw.io data visualization , painting clear pictures of corporate health. Embracing these advanced visual tools empowers every ambitious accountant to guide strategic business growth with absolute confidence.
| Fraud Category | Detection Method | Preventive Control | Recovery Step |
|---|---|---|---|
| Asset Misappropriation | Physical inventory counts and cash reconciliations | Segregation of duties and dual-authorization mandates | Civil litigation and fidelity bond claims |
| Financial Statement Fraud | Benford’s Law analysis and ratio variance testing | Independent board oversight and mandatory audit rotation | Restatement of earnings and regulatory disclosures |
| Corruption and Bribery | Vendor database auditing and lifestyle monitoring | Strict whistleblowing channels and anti-bribery policies | Contract termination and profit disgorgement |
| Cyber-Enabled Ledger Fraud | Network traffic analysis and user permission audits | Multi-factor authentication and zero-trust architecture | Cyber insurance activation and forensic isolation |
Cross-border taxation compliance demands navigating intricate international legal frameworks without incurring penalties.
Imagine a sprawling corporate empire where billions of dollars flow effortlessly across oceans daily, yet a single misplaced decimal point in a foreign ledger triggers a catastrophic cascade of legal audits. Operating on a global scale offers immense opportunities, but it exposes enterprises to the labyrinthine realities of international tax compliance. Modern tax authorities are sharpening their scrutiny, wielding advanced data analytics to track every cross-border transaction in real time.
To thrive amidst this aggressive regulatory environment, financial experts must decode complex statutes with surgical precision, ensuring that international expansion does not inadvertently invite debilitating financial penalties.
Transfer pricing regulations serve as the invisible architecture shaping how multinational corporations structure their global operations, dictating the prices charged for goods, services, and intangible property transferred between related entities under common control. When a parent company in Germany sells software to its subsidiary in the United States, tax agencies on both sides of the Atlantic scrutinize whether those internal prices mirror what independent entities would negotiate in a competitive open market.
This legal doctrine, universally recognized as the arm-length principle, prevents corporations from artificially shifting profits to low-tax jurisdictions to minimize their global tax burden. If tax authorities determine that internal pricing deviates from market reality, they possess the statutory authority to unilaterally adjust the taxable income of the entities involved, resulting in devastating secondary adjustments and severe financial penalties. Consequently, corporate structuring can no longer rely solely on operational efficiency or market penetration; it must be meticulously engineered around transfer pricing maps.
Companies must align their supply chains, functional risk profiles, and asset ownership with rigorous economic substance tests. For instance, if a shell company in a tax haven holds the legal title to a patented technology but employs zero personnel and performs no actual research, tax authorities will swiftly disregard that structure, reallocating the intellectual property profits back to the jurisdictions where the actual R&D engineers toil.
This fundamental shift means that every corporate restructuring exercise demands a parallel economic blueprint, ensuring that organizational hierarchies reflect genuine commercial rationality rather than aggressive tax avoidance strategies.
Documentation Requirements for Proving Arm-Length Transactions
Mastering the art of defense against aggressive tax audits requires building an impenetrable wall of documentation that unequivocally proves every intercompany transaction adheres strictly to market valuations. Tax administrations across the globe now demand a standardized three-tiered documentation structure, turning compliance into an exhaustive, highly regulated reporting discipline. Organizations can no longer rely on retroactive justifications; they must maintain contemporaneous records that capture the economic reality of transactions at the exact moment they occur.
This defensive architecture requires a harmonious blend of macroeconomic data, functional analysis, and rigorous financial modeling to satisfy the relentless scrutiny of global tax auditors.
The global documentation standard mandates a three-pillar approach designed to provide tax authorities with a comprehensive view of the multinational enterprise’s global business operations and transfer pricing policies. The first pillar is the Master File, which provides a high-level overview of the multinational group’s global business, including its organizational structure, supply chain dynamics, key intangibles, and intercompany financial activities. The second pillar is the Local File, which drills down into specific material intercompany transactions pertinent to that particular jurisdiction, detailing local management structures, detailed financial data of local operating entities, and comparable uncontrolled price analyses.
The third pillar is the Country-by-Country Report, requiring large multinationals with consolidated group revenues exceeding specific thresholds to annually report revenue, profit before income tax, income tax paid, and accrued, along with number of employees and tangible assets-for each jurisdiction in which the enterprise operates. Alongside these files, economic benchmarking studies utilizing databases like Amadeus or TP Catalyst must be conducted annually to identify independent comparable companies operating under similar circumstances.
Failing to produce these contemporaneous documents within statutory deadlines, which often range from thirty to sixty days upon request, invariably triggers reverse onus provisions where local tax authorities construct their own arbitrary assessments, leaving the corporation with virtually no room for appeal.
Visualizing a comprehensive transfer pricing documentation repository reveals a secure, highly encrypted digital dashboard glowing softly on a compliance officer’s multi-monitor workstation. On the left side of the screen, interactive organizational charts map out cross-border subsidiary linkages across fifty countries, color-coded by risk levels ranging from emerald green for low-risk jurisdictions to crimson red for high-scrutiny audit zones. In the center, a vast matrix displays contemporaneous benchmarking studies, complete with statistical median ranges, interquartile ranges, and regression analysis curves that validate the arm’s-length nature of internal royalty rates.
Modern accounting demands sharp analytical talents and unwavering precision. As financial data streams flow relentlessly into digital ledgers, professionals must master essential tools, effortlessly utilizing how to alphabetise in excel to turn chaotic rows into crystal clear insights. Cultivating this organizational prowess ultimately elevates your career trajectory, transforming raw numbers into powerful narratives of corporate success.
On the right, automated compliance tracking calendars display real-time countdown timers for Country-by-Country reporting deadlines, ensuring that no regulatory filing slips through the cracks of a busy multinational finance department.
Common Pitfalls During Multi-Jurisdictional Value-Added Tax Filings
Navigating the turbulent waters of multi-jurisdictional indirect taxation often feels like walking through a minefield where the rules shift unpredictably with every foreign border crossed. Value-added tax and goods and services tax systems are notoriously unforgiving, punishing administrative oversights with heavy interest charges and compounding penalties that can silently erode profit margins. Financial professionals must remain hyper-vigilant, recognizing that indirect tax compliance is fundamentally different from direct corporate income tax, requiring real-time transactional accuracy rather than retrospective annual reconciliations.
To highlight the operational vulnerabilities that frequently trap unwary multinational corporations during cross-border trade, the following points illustrate the most critical pitfalls encountered in multi-jurisdictional indirect tax management:
- Misclassifying digital services and software-as-a-service deliveries, leading to severe discrepancies between destination-based consumption tax rules and origin-based invoicing systems.
- Failing to secure valid, auditable proof of export for cross-border physical shipments, which routinely results in the denial of zero-rating privileges and subsequent local tax assessments.
- Ignoring local registration thresholds and permanent establishment triggers when deploying remote workforce personnel or temporary digital nomads to foreign operational hubs.
- Overlooking complex reverse-charge mechanism requirements on imported business-to-business services, causing mismatched input tax credit claims and delayed refunds.
- Neglecting foreign currency conversion timing differences between the date of invoice issuance and the official customs clearance exchange rate mandated by local statutory bodies.
Accurate transactional data capture and rigorous digital reconciliation are the ultimate shields against the compounding financial devastation of indirect tax penalties.
Step-by-Step Procedure for Resolving Double Taxation Disputes
When two sovereign nations simultaneously claim the right to tax the exact same corporate revenue stream, the resulting economic friction threatens to strangle international trade and investment. Resolving these harrowing double taxation deadlocks requires moving past traditional litigation and entering the specialized diplomatic sphere of international tax dispute resolution. Multinational enterprises must master the formal pathways established by bilateral tax treaties and global regulatory consensus to reclaim their trapped capital and restore financial equilibrium.
The formal journey of dismantling a double taxation dispute begins the moment a taxpayer receives a primary adjustment notice from a local tax authority that creates economic or juridical double taxation. The foundational phase requires filing a formal request for a Mutual Agreement Procedure under the relevant bilateral tax treaty or the multilateral instrument framework, typically within a strict three-year statutory window from the first notification of the action resulting in taxation not in accordance with the provisions of the convention.
Once the competent authorities of the respective treaty partner countries formally accept the case, they initiate direct government-to-government negotiations behind closed doors to endeavor to resolve the case by mutual agreement. During this negotiation phase, the taxpayer acts primarily as an information provider, supplying extensive transactional evidence, transfer pricing studies, and economic justifications to both domestic and foreign tax officials.
If the respective competent authorities fail to reach a mutually satisfactory consensus within a specified timeframe, which traditionally spans twenty-four months, modern international frameworks increasingly mandate binding arbitration provisions where an independent panel reviews the arguments and delivers a definitive, non-appealable verdict. Throughout this intricate bureaucratic marathon, financial executives must maintain flawless synchronization between the disputing jurisdictions, ensuring that any domestic tax suspension or collection deferral requests are actively managed to prevent cash flow strangulation while the diplomatic resolution unfolds.
ESG metrics integration transforms traditional corporate reporting into a comprehensive measure of sustainable business health.

Source: theknowledgeacademy.com
Modern corporate accountability has evolved far beyond traditional profit and loss statements, requiring financial professionals to weave environmental, social, and governance factors directly into the fabric of enterprise valuation. Stakeholders no longer look solely at quarterly earnings reports; they demand a transparent, panoramic view of how long-term ecological stewardship and ethical governance drive enduring business resilience. This profound shift redefines ledger systems, turning non-financial data into critical economic indicators that shape investor sentiment and capital allocation.
The quantification and recording of environmental liabilities on corporate balance sheets demand rigorous accounting precision, transforming ecological risks into tangible financial obligations. When a corporation incurs an environmental cleanup obligation, such as remediating a contaminated manufacturing site or retiring offshore drilling infrastructure, accountants must calculate the net present value of the future cash outflows required for restoration. These estimates rely heavily on probabilistic cash flow modeling and engineering assessments that predict the timing and cost of remediation efforts.
Under established frameworks like International Accounting Standard 37 and ASC 410 in the United States, companies recognize a liability and a corresponding asset capitalization when a legal or constructive obligation arises from past events. For instance, global energy giants routinely provision billions of dollars for asset retirement obligations, adjusting these figures annually to reflect shifting inflation rates, technological advancements in remediation, and evolving regulatory mandates.
Visualizing this process reveals a meticulous ledger entry where environmental degradation is instantly translated into a measurable capital liability, ensuring that future generations of executives cannot hide ecological debts off the balance sheet. This disciplined translation bridges the gap between planetary health and fiscal reality, giving markets an honest appraisal of corporate exposure.
Environmental liabilities are not merely ethical concerns; they are quantifiable financial commitments that directly alter enterprise value and balance sheet integrity.
Auditing standards applied to non-financial carbon emission disclosures
The verification of non-financial carbon emission disclosures has transitioned from a voluntary corporate social responsibility exercise into a heavily regulated assurance discipline. Independent auditors now apply rigorous frameworks, such as ISAE 3000 and ISO 14064, to scrutinize greenhouse gas inventories spanning Scope 1, Scope 2, and Scope 3 emissions. This assurance process requires gathering robust audit evidence, testing internal data collection controls, and challenging the emission factors used to translate physical activity data into carbon dioxide equivalents.
Auditors examine supply chain documentation, energy utility invoices, and continuous emissions monitoring systems with the same skeptical eye traditionally reserved for cash accounts and revenue recognition. As regulatory bodies like the International Sustainability Standards Board enforce stricter reporting mandates, the demand for high-level assurance grows exponentially, ensuring that corporate net-zero claims are backed by verifiable data rather than empty marketing rhetoric.
Organizations face intense public scrutiny regarding their carbon footprints, making the reliability of non-financial disclosures paramount to maintaining investor trust and avoiding severe regulatory penalties. Auditors deploy specialized multidisciplinary teams to re-perform calculations, evaluate estimation uncertainties, and verify organizational boundaries using operational and financial control approaches. A vivid mental picture of this auditing environment involves forensic data analysts side-by-side with environmental scientists, tracing millions of tons of carbon from factory floor sensors up to executive sustainability dashboards, ensuring every metric withstands public and regulatory interrogation.
The following table illustrates the multifaceted relationship between environmental metrics, operational measurement tools, recognized reporting frameworks, and their ultimate impact on corporate valuation.
| ESG Metric Type | Measurement Tools | Reporting Standards | Impact on Valuation |
|---|---|---|---|
| Carbon Emissions | Continuous Emissions Monitors, Life Cycle Analysis Software | GHG Protocol, ISSB S2, TCFD | Directly influences cost of capital and carbon tax exposure liabilities. |
| Water Usage | Flow Meters, Watershed Risk Assessment Models | SASB, GRI 303 | Affects operational continuity and community license to operate in arid regions. |
| Waste Management | Supply Chain Audits, Material Flow Cost Accounting | GRI 306, Zero Waste Certification | Reduces disposal expenses and enhances brand equity among conscious consumers. |
| Biodiversity Impact | Satellite Imagery Analysis, Ecosystem Services Valuation | TNFD, Science Based Targets for Nature | Mitigates regulatory fines and preserves long-term resource availability. |
Collaborative workflow between financial auditors and environmental scientists during materiality assessments
Executing a comprehensive materiality assessment requires bridging two distinct professional worlds, merging the quantitative discipline of financial auditing with the empirical rigor of environmental science. Financial auditors understand regulatory thresholds, materiality dollar limits, and internal control structures, whereas environmental scientists possess the deep ecological knowledge needed to identify subtle, long-term risks such as biodiversity loss or chronic pollution seepage. During joint materiality workshops, these professionals evaluate both financial impact and planetary impact, a concept known as double materiality.
This collaborative workflow ensures that risks dismissed as immaterial through a purely short-term financial lens are properly re-evaluated for their potential to trigger catastrophic reputational damage or regulatory shutdowns.
The synergy between these disciplines transforms sustainability reporting from a siloed compliance task into a deeply integrated strategic review that protects the organization from unforeseen shocks. Environmental scientists supply the raw data regarding ecological footprints and resource depletion rates, while financial auditors translate those scientific models into risk-weighted financial scenarios and disclosure requirements. Visualizing this dynamic partnership reveals teams of accountants and ecologists standing over facility maps and financial ledgers, rigorously debating the long-term economic viability of supply chains situated in climate-vulnerable zones.
This rigorous cross-functional alignment guarantees that modern corporate reporting reflects a true and fair view of sustainable business health for investors and regulators alike.
Executive advisory competencies enable number crunchers to transition into trusted boardroom strategists.
Modern finance professionals are stepping out of the shadows of traditional spreadsheets and taking center stage where critical corporate destinies are shaped. Transforming raw data into a compelling narrative is no longer just a soft skill; it is the ultimate catalyst for executive capital allocation and high-stakes decision-making. Imagine stepping into a sleek, glass-walled boardroom where the tension is palpable, and millions of dollars hang in the balance of a single strategic choice.
The traditional language of debits and credits often falls flat among visionary chief executives and board members who crave clarity over complexity. By mastering executive advisory competencies, financial leaders bridge this chasm, turning cold digits into warm, actionable insights that inspire bold investments and safeguard enterprise longevity.
Financial storytelling acts as the ultimate bridge between historical ledger data and future strategic vision, fundamentally steering how leadership teams deploy capital. When top-tier financial advisors present a capital allocation plan, they do not merely recite revenue growth percentages or operational expenditure burn rates; they weave an engaging narrative about risk, opportunity, and market momentum. This method taps into the cognitive psychology of decision-makers, who process strategic scenarios much faster when presented as a coherent journey rather than an endless array of tabular data.
For instance, when streaming giant Netflix transitioned its massive capital expenditure from physical DVD logistics to proprietary streaming infrastructure and original content production, the finance team had to paint a vivid picture of shifting consumer behavior. They framed the capital outlay not as an expense spike, but as a survival narrative against impending industry obsolescence. By contextualizing capital expenditure through a storyline of market dominance and defensive moats, leadership gained the psychological safety required to approve billions in strategic investments.
Effective financial storytelling strips away the intimidating jargon of balance sheets, replacing it with a laser-focused narrative arc that highlights the cost of inaction alongside the lucrative rewards of calculated risk-taking.
Translation Techniques For Non-Financial Stakeholders
Bridging the communication gap between meticulous accountants and creative operational leaders requires a deliberate mastery of translation techniques that demystify complex variance reports. Stakeholders outside the finance department frequently tune out when confronted with dense columns of favorable and unfavorable variances, viewing them as alien dialect rather than operational feedback. To combat this cognitive overload, elite advisors utilize analogical framing, anchoring abstract financial deviations to tangible, everyday business realities that department heads manage directly.
Instead of explaining a material labor variance through standard costing terminology, a seasoned advisor might describe it as the direct financial footprint of onboarding bottlenecks and overtime inefficiencies within the supply chain. Visual scaffolding also plays a pivotal role, transforming static spreadsheets into dynamic heat maps and trend lines that instantly spotlight operational friction points. Furthermore, stripping away unnecessary technical minutiae allows executives to focus exclusively on the core drivers of performance anomalies, fostering an environment of collaborative problem-solving rather than defensive justification.
To successfully convey the true meaning of financial variances during executive briefings, finance professionals must consistently apply specific communicative strategies that resonate across diverse departmental backgrounds.
- Contextualizing raw percentage deviations by pairing them immediately with the underlying physical operational events that triggered them.
- Employing visual color-coded materiality thresholds that instantly direct executive attention to high-impact budgetary anomalies rather than minor rounding discrepancies.
- Framing budget variances through the lens of future operational capacity rather than dwelling purely on historical financial penalties.
- Translating accounting accruals and non-cash adjustments into clear cash-flow consequences that operational leaders can directly influence and control.
Core Components Of Compelling Quarterly Financial Presentations, Skills needed for accounting
Delivering a quarterly financial presentation that commands the undivided attention of the boardroom requires a meticulous architecture designed to balance rigorous compliance with forward-looking ambition. A truly compelling briefing transcends the traditional duty of merely reporting what happened in the past three months, evolving instead into an interactive roadmap for the quarters ahead. Modern executives expect financial presentations to feel less like a compliance ritual and more like an inspiring State of the Union address for the enterprise.
Every slide and spoken word must be carefully calibrated to answer the unvoiced anxieties of the board while shining a bright light on emerging strategic opportunities. When structured correctly, the quarterly presentation becomes the heartbeat of corporate governance, aligning diverse stakeholders around a unified financial truth.
Crafting a presentation that resonates at the executive level demands a rigorous adherence to structural pillars that prioritize clarity, strategic insight, and actionable foresight above mere data density.
- An executive summary dashboard that immediately answers the primary health indicators of the business within the first three minutes of the meeting.
- A narrative-driven variance analysis that clearly separates one-off market anomalies from structural operational shifts requiring structural intervention.
- A forward-looking predictive scenario analysis outlining best-case, expected, and worst-case financial trajectories based on current macroeconomic indicators.
- A crystal-clear capital allocation update tracking the return on investment for previously approved strategic projects and ongoing corporate initiatives.
Methods For Aligning Departmental Spending Targets With Corporate Objectives
Organizational strategy often falters not from a lack of visionary ideas, but from a chronic misalignment between overarching corporate goals and daily departmental budgets. When individual business units operate in financial silos, marketing may aggressively pursue aggressive customer acquisition while procurement simultaneously implements severe cost-cutting measures that compromise product quality. Resolving this friction demands sophisticated alignment methodologies that embed high-level corporate mission objectives directly into the DNA of localized operational spending targets.
By utilizing advanced frameworks such as Objectives and Key Results integrated tightly with rolling forecasts, finance teams ensure every dollar spent actively pushes the enterprise closer to its ultimate strategic horizon. This tactical harmonization transforms the annual budgeting process from an exhausting negotiation into a synchronized march toward shared corporate triumph.
Financial advisors utilize specific structural methodologies to ensure departmental budgets faithfully reflect the broader strategic ambitions of the executive leadership team without stifling operational agility.
- Implementing driver-based budgeting models that tie departmental resource allocation directly to specific key performance indicators tied to corporate mission milestones.
- Establishing cross-functional resource allocation committees where finance, human resources, and operations jointly evaluate spending requests against strategic priority matrices.
- Deploying zero-based budgeting exercises annually to systematically strip away legacy expenses that no longer serve the current strategic direction of the firm.
- Creating dynamic funding pools that reward departments demonstrating exceptional efficiency in advancing overarching environmental, social, and governance targets.
Strategic financial advisory is the art of translating the language of accounting into the vision of leadership, ensuring every dollar deployed tells a story of sustainable growth and enduring enterprise value.
Last Recap: Skills Needed For Accounting
Mastering these multidimensional competencies unlocks extraordinary potential, empowering financial professionals to step out of the shadows of routine calculation and into the vital role of trusted executive strategists. By embracing digital automation, mastering international tax frameworks, and championing sustainable business health, today’s practitioners are not merely recording history—they are actively engineering a brighter, more resilient future for the global marketplace.
